Quick Answer
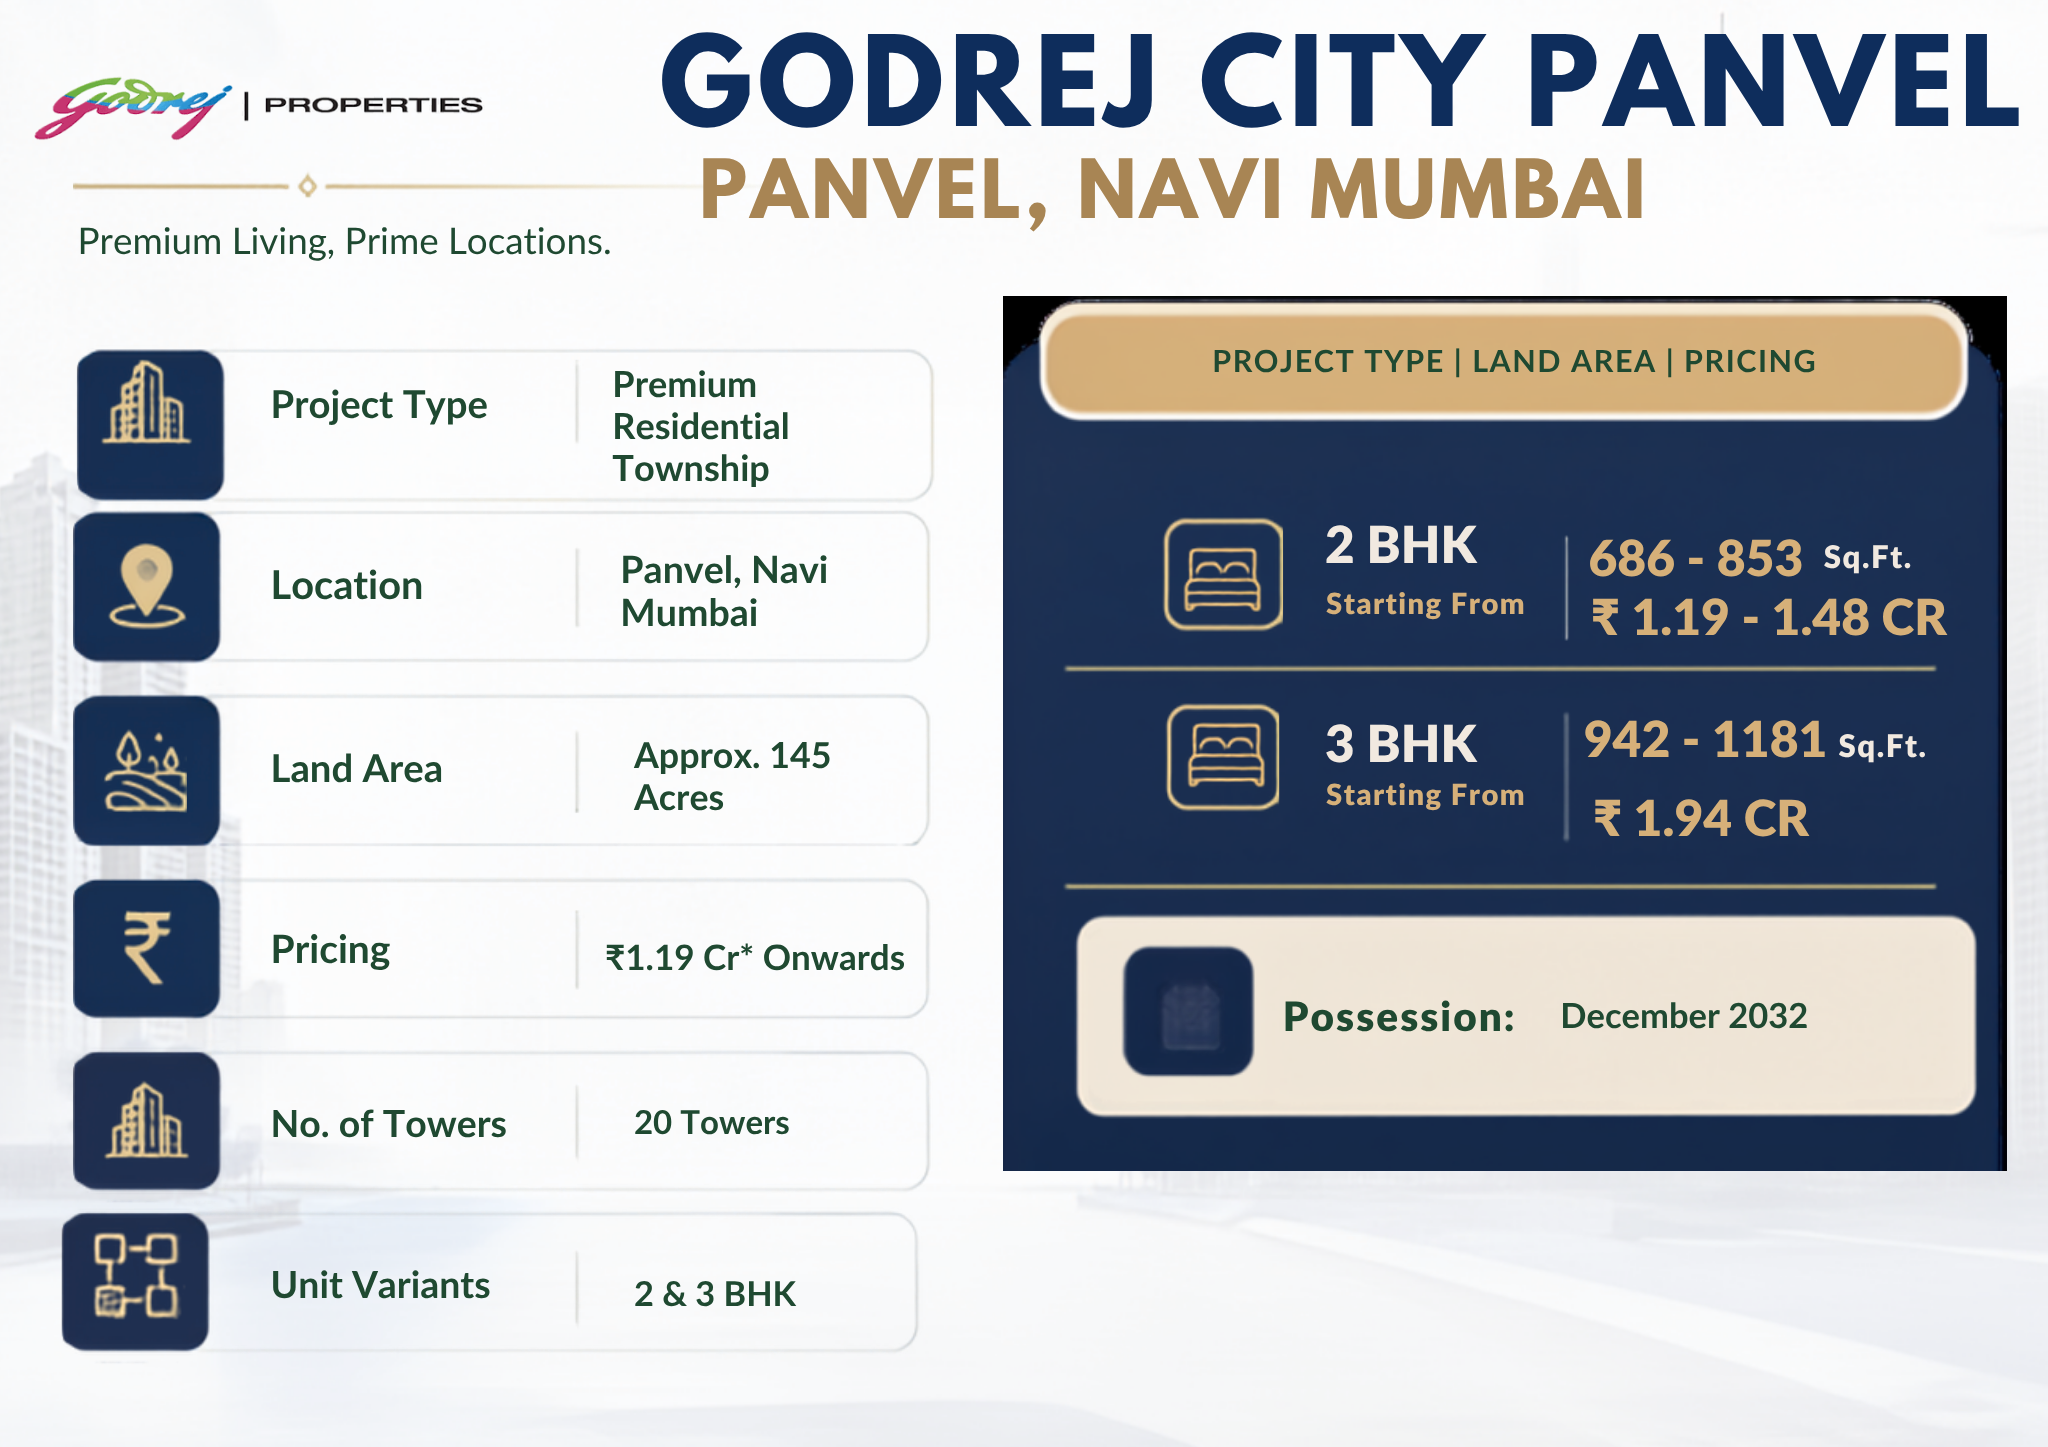
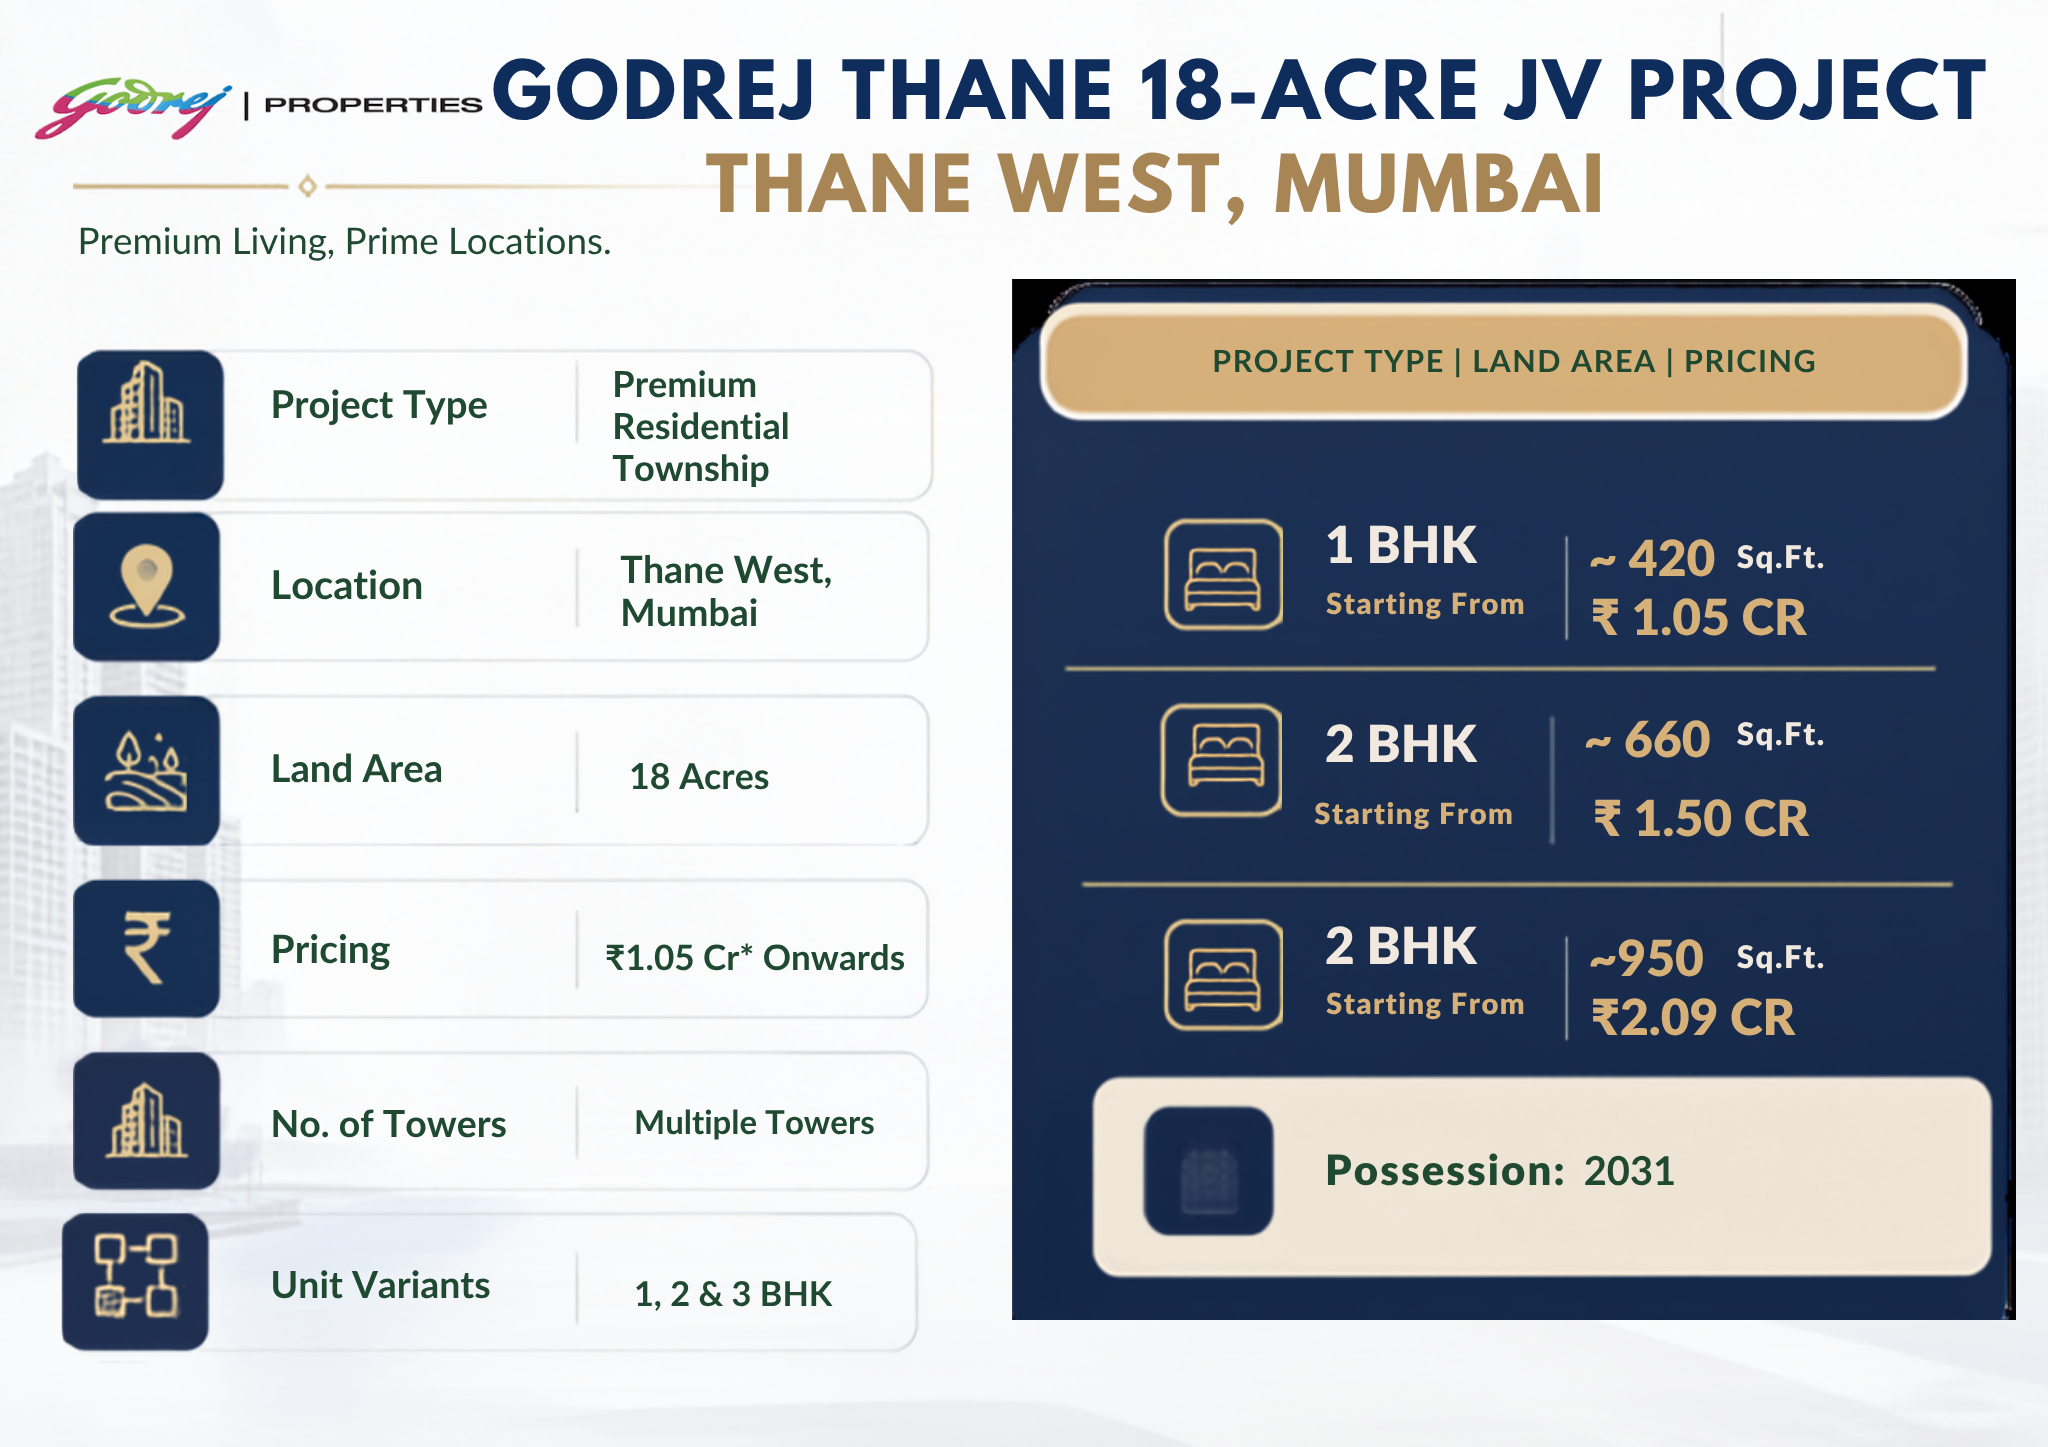
Related Godrej projects nearby:
Godrej Bandra Reclamation — Sea-Facing 4 BHK, Mumbai →Godrej Trilogy – Worli, Mumbai →Godrej Horizon – Wadala Mumbai →
On pure numbers, renting is cheaper than buying in most of Mumbai in 2026. Price-to-rent ratios run about 21x to 35x, and an 8% loan costs roughly twice the rent. Over 10 years, buying a Rs 1.5 crore Kandivali East flat beats renting and investing the difference only if prices rise about 6–7% a year. Buy if you will stay 10+ years and want certainty.
The rent vs buy in Mumbai question got sharper in October 2026. On 7 October the RBI raised the repo rate to 5.50%, and lenders such as Bank of Baroda moved their home loan rates above 8% within days. Prices are rising too: Knight Frank put Mumbai’s weighted average at Rs 37,064 per sq ft in Q3 2026, up 5% in a year. Meanwhile, a 2 BHK in a gated Kandivali East society still rents for roughly Rs 35,000 to Rs 55,000 a month.
So the monthly maths favours renting, and the long-term maths depends on how fast prices rise. Most online calculators skip the parts that decide the answer. They leave out stamp duty, they don’t invest the renter’s savings, or they assume a growth rate nobody can promise.
We at Godrej Properties MMR have built a 10-year comparison for a typical western-suburbs flat, set out price-to-rent ratios across five MMR markets, and worked out the break-even growth rate at which buying beats renting.
Rent vs Buy in Mumbai: Price-to-Rent Ratios by Locality
The price-to-rent ratio is the purchase price divided by a year’s rent. Below about 20x, buying usually looks good on paper. Above 30x, renting is clearly cheaper year to year, and buying needs strong price growth to catch up. Most of Mumbai sits in the high-20s to mid-30s.
| Locality | Typical 2026 price | Typical 2 BHK rent / month | Price-to-rent | Gross yield |
|---|---|---|---|---|
| Navi Mumbai (Kharghar) | Rs 17,500–18,500 per sq ft; 2 BHK about Rs 1 Cr | Rs 32,000–40,000 | About 21–26x | 3.9–4.8% |
| Thane West | Rs 17,500–20,350 per sq ft; 2 BHK about Rs 82 lakh–1.2 Cr | Rs 24,000–32,000 | About 28x | 3.5–4.5% |
| Kandivali East | About Rs 28,550 per sq ft; 2 BHK about Rs 1.5 Cr | Rs 35,000–55,000 | About 27–35x | 2.5–3.5% |
| Powai | About Rs 40,850 per sq ft; 2 BHK about Rs 2.6–3 Cr | Rs 55,000–90,000 | About 30–35x | About 3% |
| Worli (3 BHK) | About Rs 72,000–74,000 per sq ft | Rs 2.6–3.3 lakh (3 BHK, premium towers) | About 30–40x | 2–3% |
Price data comes from 99acres and Homebazaar averages and our own locality tracking. Rents come from live listings on NoBroker, Square Yards and RentU, and yields from the Magicbricks April–June 2026 rental index. Listing rents run above agreed rents, so treat the ranges as a guide. Navi Mumbai’s 4.8% yield is the strongest in the region, as our Mumbai rental market 2026 report explains.
The 10-Year Numbers: A Kandivali East Example
Here is a like-for-like test on a Rs 1.5 crore 2 BHK in Kandivali East. The buyer puts down 20% (Rs 30 lakh), pays 6% stamp duty and registration (about Rs 9.3 lakh), and spends about Rs 1.5 lakh on legal and other costs. That is Rs 40.8 lakh upfront. The Rs 1.2 crore loan runs 20 years at 8%, for an EMI of about Rs 1,00,373. Society maintenance starts at Rs 5,500 a month.
The renter pays Rs 38,000 a month for the same flat, with rent rising 5% a year. The renter invests the Rs 40.8 lakh on day one, and each year also invests the difference between the owner’s costs and the rent, at 9% a year.
| After 10 years | Buyer | Renter |
|---|---|---|
| Cash paid out (EMI + maintenance, or rent) | About Rs 1.29 Cr | About Rs 57.4 lakh |
| Home value at 5% a year | About Rs 2.44 Cr | — |
| Loan still outstanding | About Rs 82.7 lakh | — |
| Net wealth from the decision | About Rs 1.62 Cr (home equity) | About Rs 2.08 Cr (investments) |
| Break-even price growth for buying to win | About 7% a year if investments earn 9%; about 6% if they earn 7% | |
At 5% a year, roughly the citywide rise Knight Frank reported for Q3 2026, the renter ends about Rs 46 lakh ahead. At 7% growth, the two are level, with home equity of about Rs 2.12 crore. The same test on a Rs 1 crore Thane flat renting at Rs 30,000 gives a break-even of about 6.5% a year. The model leaves out a few items, so read it as a direction, not a verdict. Owners save some tax under the old regime, and owners pay repairs. Renters pay brokerage on each lease, and their investment gains are taxed.
Renting only wins if the renter actually invests the difference every year. A renter who spends it ends the decade with nothing, while the owner still holds about Rs 1.6 crore of equity even at 5% growth.
What Changes the Answer
Five inputs decide the rent vs buy in Mumbai result. A small change in any of them can flip the outcome, so test your own case against each:
- Price growth in your micro-market. The single biggest driver. In our model each 1% of annual growth is worth roughly Rs 25 lakh to the buyer over 10 years.
- Investment discipline. The renting case assumes the money is invested every year, not spent.
- Holding period. Stamp duty of 6% and buying costs need years to recover. Under five years, renting almost always wins.
- Loan rate. Each 0.25% rise adds about Rs 1,850 a month to a Rs 1.2 crore EMI at today’s rates.
- Rent growth. Navi Mumbai rents rose 11.1% in a year to June 2026. Fast rent growth shortens the gap quickly.
- Down payment. A larger down payment lowers the EMI but raises the return the renter earns on the same cash.
When Buying Wins in Mumbai
The numbers favour renting on average, but buyers who pick the right location at the right time often beat the averages. Buying tends to win in three situations.
First, when infrastructure is about to change a locality’s commute. Kandivali East and Borivali East sit next to the Magathane portal of the Thane–Borivali twin tunnel, which will cut the Borivali–Thane drive to about 15 minutes. Locality averages in these pockets have already been moving faster than the city: average rates at one Kandivali East Godrej project rose from about Rs 26,100 to Rs 29,100 per sq ft in a single quarter of 2026. If you believe the Thane Borivali tunnel completion date will hold within a year or two of target, owning ahead of it is a reasonable bet on the 6–7% growth the break-even needs.
Second, when the price-to-rent ratio is low. Navi Mumbai at about 21–26x needs much less price growth to justify buying than Powai or Worli. Third, when you plan to stay. Families with school-age children who expect to stay 10 to 15 years avoid repeated brokerage, deposits and forced moves, and that security has value no spreadsheet captures.
Our verdict: Rent if you might move within five years or the EMI would exceed 40% of take-home pay. Buy if you will stay 10 years or more, your down payment is ready, and the locality has a clear growth trigger such as a new metro, tunnel or road.
A 7-Point Rent-or-Buy Checklist
- Calculate the price-to-rent ratio for the exact building, using three live rent listings and three recent sale prices.
- Set your holding period honestly. If it is under seven years, lean towards renting.
- Price the loan at 8% or your sanctioned rate, whichever is higher.
- Add every upfront cost: 6% stamp duty (5% for women buyers), registration, legal fees, brokerage and interiors.
- Check the growth trigger. Name the metro line, tunnel or office cluster that will lift prices, and its realistic date.
- Commit to investing the gap if you rent. Set up an automatic monthly investment for the difference.
- Stress-test the EMI at 1% higher than today and check it still fits under 40% of take-home pay.
Where Godrej Projects Fit the Rent vs Buy Picture
Godrej Properties Limited, a third-party developer active across the MMR, has projects in several of the markets above. In Kandivali East, Godrej Reserve is an 18.6-acre development of 2, 3 and 4 BHK homes from about Rs 2.35 crore, close to the tunnel’s Magathane portal. Buyers who see that portal as a growth trigger may find the break-even growth rate easier to reach there. Our Kandivali East property prices guide tracks the locality’s rates.
For buyers still comparing, our Godrej Mumbai project reviews set the main projects side by side. Developer background is on the Godrej Properties Limited website.
Frequently Asked Questions
Q: Is it better to rent or buy in Mumbai in 2026?
On monthly cost, renting is cheaper almost everywhere: an EMI at 8% is roughly twice the rent on the same flat. Over 10 years, buying wins only if prices rise about 6–7% a year, or if you would not have invested the savings. Long stays and strong growth triggers favour buying.
Q: What is a good price-to-rent ratio for buying?
Below about 20x, buying usually beats renting. Between 20x and 30x it depends on growth and holding period. Above 30x, renting is clearly cheaper year to year. Navi Mumbai sits near 21–26x, Thane near 28x, and Kandivali East, Powai and Worli near 30x or more.
Q: How long should I stay for buying to make sense?
At least seven to ten years in most of Mumbai. Stamp duty of 6%, registration and other buying costs add roughly 7% to the price, and they take years of appreciation to recover. Under five years, renting nearly always comes out ahead.
Q: Did the October 2026 RBI rate hike change the answer?
It nudged it towards renting. The repo rate rose to 5.50% on 7 October 2026, and several banks moved home loan rates above 8%. On a Rs 1.2 crore loan, each 0.25% adds about Rs 1,850 a month to the EMI.
Q: What rental yield can I expect if I buy to let?
Gross yields run about 2–3% in Worli and Powai, 2.5–3.5% in Kandivali East, 3.5–4.5% in Thane West and up to 4.8% in Navi Mumbai. Net yields after maintenance, brokerage and vacancy are usually about 1 percentage point lower.
Q: Does the home loan tax benefit tip the balance?
Only modestly. Under the old regime a self-occupied home allows up to Rs 2 lakh of interest and Rs 1.5 lakh of principal a year. Under the new default regime there is no deduction for a self-occupied home, so most salaried buyers get little tax help.
Conclusion
Rent vs buy in Mumbai in 2026 comes down to time and growth. Renting is cheaper every month, and over a decade it wins unless prices rise around 6–7% a year. Buying wins for people who stay long, invest poorly, or buy ahead of a real infrastructure trigger at a reasonable price-to-rent ratio. Run the numbers for the specific building, not the city average.
If you are leaning towards buying, explore current projects at Godrej Properties MMR and book a site visit. Our team can share rent and resale comparables for the building you are considering.